Skip to main content Skip to search

Posts by Mina Baselyous

Bookkeeping Blog Banner Pinnacle Accounting & Advisory

What Is Bookkeeping and How Your Accountant Can Help

Bookkeeping is the day-to-day recording and organising of a business’s financial transactions, including sales, purchases, payments and receipts. Accurate bookkeeping is the foundation of every business: without clean, up-to-date records there are no meaningful reports and no reliable basis for decisions or tax.

Bookkeeping is one of the most important, and most misunderstood parts of running a business.

Many business owners see bookkeeping as data entry or an administrative task. In reality, good bookkeeping is the foundation of cash flow control, tax compliance, and informed decision-making. Poor bookkeeping, on the other hand, is one of the leading causes of ATO issues, cash shortages, and business stress. Understanding what is bookkeeping is crucial for every business owner. What is bookkeeping is not just a task; it is a vital aspect of business management.

In this article, we explain what bookkeeping is, why it matters, and how working with the right accountant transforms bookkeeping from a chore into a strategic advantage. We will clarify what is bookkeeping and its importance to business success.

This article will explore what is bookkeeping, why it matters, and how working with the right accountant transforms it from a chore into a strategic advantage. Understanding what is bookkeeping will help you appreciate its critical role in your business.


What Is Bookkeeping?
1 13 Pinnacle Accounting & Advisory

Bookkeeping is the process of recording, organising, and maintaining a business’s financial transactions.

To further understand what is bookkeeping, let’s delve into its key components.

This includes:

  • recording income and expenses
  • reconciling bank accounts
  • managing invoices and receipts
  • tracking GST, PAYG, and payroll transactions
  • maintaining accurate financial records

Accurate bookkeeping ensures your financial data is complete, current, and reliable — which is essential for tax reporting and business planning.


Why Bookkeeping Is Critical for Businesses

Bookkeeping affects far more than just compliance.

Good bookkeeping:

  • supports accurate BAS and IAS lodgements
  • improves cash flow visibility
  • reduces ATO audit risk
  • enables better pricing and staffing decisions

Poor bookkeeping often leads to:

  • late or incorrect BAS lodgements
  • GST and PAYG shortfalls
  • unexpected tax bills
  • compliance penalties

Understanding reporting obligations is essential, particularly for GST-registered businesses, as explained in
👉 What Is a BAS (Business Activity Statement)?


Bookkeeping and Cash Flow Management
cash flow theme Pinnacle Accounting & Advisory

One of the biggest problems we see is businesses operating without real-time financial visibility.

Without proper bookkeeping:

  • business owners don’t know how much cash is actually available
  • tax funds are accidentally spent
  • payroll and super obligations are underestimated

Strong bookkeeping works hand-in-hand with cash flow systems, including separating operating money from tax obligations — a concept outlined in
👉 The 6 Bank Accounts Every Business Owner Needs


How Bookkeeping Supports Tax Compliance
images 10 Pinnacle Accounting & Advisory

Accurate bookkeeping ensures:

  • GST is reported correctly
  • PAYG withholding is accurate
  • income and deductions are supported by records
  • superannuation obligations are tracked

When bookkeeping is incomplete or inconsistent, businesses are far more likely to attract ATO attention. This risk is explored further in
👉 ATO Audit Support for Businesses: What It Is and Why It Matters


How Your Accountant Helps With Bookkeeping
images 11 Pinnacle Accounting & Advisory

At Pinnacle Accounting & Advisory, we don’t just “check the numbers” at year end — we help businesses use bookkeeping as a decision-making tool.

Your accountant can help by:

  • setting up bookkeeping systems correctly from the start
  • ensuring transactions are coded accurately
  • reviewing reconciliations regularly
  • identifying errors before they become costly problems
  • aligning bookkeeping data with tax planning strategies

This proactive approach helps business owners move from reacting to problems to planning with confidence.


Bookkeeping and Business Strategy

Bookkeeping data feeds directly into:

  • profit analysis
  • pricing decisions
  • staffing decisions
  • growth planning

When bookkeeping is accurate, financial reports become meaningful — not just compliance documents.

This is why understanding your numbers is so powerful, as discussed in
👉 The Truth About Sales & Accounting: Why Knowing Your Numbers Is the Ultimate Business Strategy


Common Bookkeeping Mistakes Businesses Make

Some of the most common bookkeeping mistakes include:

  • mixing personal and business expenses
  • falling behind on reconciliations
  • incorrect GST treatment
  • poor recordkeeping
  • relying solely on software without review

Software helps — but it doesn’t replace professional oversight.


Bookkeeping Is Not “Set and Forget”

Bookkeeping is an ongoing process, not a once-a-year task.

Regular review ensures:

  • problems are identified early
  • cash flow remains under control
  • tax outcomes are optimised
  • compliance risk is reduced

Businesses that treat bookkeeping seriously experience far fewer surprises at tax time.


Final Thoughts

Bookkeeping is the backbone of a healthy business.

When done properly, it:

  • provides clarity
  • supports compliance
  • enables growth
  • reduces stress

With the support of a proactive accountant, bookkeeping becomes more than recordkeeping, it becomes a strategic asset that supports better decisions and long-term success.

What is bookkeeping in a business?

Bookkeeping is the process of recording and maintaining a business’s financial transactions, including income, expenses, and tax-related records.

Do I still need an accountant if I use bookkeeping software?

Yes. Software records data, but an accountant ensures accuracy, compliance, and strategic use of that data for tax planning and decision-making.

How often should bookkeeping be reviewed?

Ideally, bookkeeping should be updated regularly and reviewed monthly or quarterly to ensure accuracy and avoid issues later.

Can poor bookkeeping lead to ATO penalties?

Yes. Inaccurate or incomplete records can result in incorrect BAS lodgements, audits, penalties, and interest charges.

General Advice Disclaimer: The information in this article is general in nature and does not constitute personal financial, tax, or legal advice. Your individual circumstances will determine the most appropriate approach for you. Please consult a registered tax adviser or CPA before acting on anything in this article. Liability limited by a scheme approved under Professional Standards Legislation.

Frequently Asked Questions

What is bookkeeping?

Bookkeeping is the process of recording, organising and reconciling a business’s financial transactions, such as sales, expenses, payments and receipts. It keeps your financial records accurate and up to date, forming the foundation for reporting, tax and decision-making.

What is the difference between bookkeeping and accounting?

Bookkeeping records and organises daily transactions. Accounting interprets that data to produce reports, advise on tax and structure, and support decisions. Bookkeeping is the foundation; accounting is the analysis and strategy built on top of it.

Why is bookkeeping important for small business?

Without accurate bookkeeping there are no reliable reports, so you cannot see your true profit, cash flow or tax position. Clean records reduce stress at tax time, support better decisions, and are essential if you ever seek finance or sell the business.

Should I do my own bookkeeping?

Many owners start out doing their own, but as the business grows it usually pays to use software and a bookkeeper or accountant. Getting it right frees your time and ensures the records are accurate enough to base real decisions on.

This article contains general advice only and does not take into account your specific circumstances. Please speak with a qualified accountant or tax adviser before making financial decisions.

Loading posts…

About Mina Baselyous

Mina Baselyous is a Chartered Tax Advisor (CTA), Certified Practising Accountant (CPA) and Registered Tax Agent based in Melbourne. He founded Pinnacle Accounting & Advisory to give small and medium business owners the proactive, strategic advice most accountants never offer. Read Mina’s full profile and credentials.

LinkedIn  |  Instagram

Read more
Copy of Family Trust Blog banner Pinnacle Accounting & Advisory

GST Coding Explained: How to Correctly Code GST on Business Transactions

GST coding is how you classify each transaction for GST purposes in your accounting software, such as GST on sales, GST on purchases, GST-free, or input-taxed. Correct GST coding ensures your BAS is accurate and you claim the right GST credits. Miscoding is one of the most common causes of BAS errors.

Incorrect GST coding is one of the most common issues we see in small and medium businesses, and one of the easiest ways to create BAS errors, cash flow problems, and ATO risk.

Many business owners assume accounting software will “work it out automatically.” In reality, GST coding decisions still rely on human understanding, and errors often go unnoticed until a BAS review or audit.

In this article, we explain how GST works, how to correctly code GST on common transactions, and how your accountant helps ensure GST is reported accurately.


What Is GST Coding?

680f050ae59ad68818884a8c flow chart and BAS coding in Xero Pinnacle Accounting & Advisory

GST coding refers to assigning the correct GST treatment to each transaction in your accounting system.

Correct GST coding ensures:

  • GST collected and paid is accurate
  • BAS figures are correct
  • cash flow is not distorted
  • ATO compliance risk is reduced

Incorrect coding can result in:

  • overpaying GST
  • underpaying GST
  • amended BAS lodgements
  • penalties and interest

Common GST Codes in Australia

Most accounting software uses similar GST categories, including:

  • GST on Income – 10% GST charged on taxable sales
  • GST on Expenses – GST credits claimed on business purchases
  • GST-Free – no GST applies
  • Input-Taxed – no GST charged and no GST credits claimable
  • No GST – transactions outside the GST system

Understanding the difference between these categories is essential.


GST Coding on Sales Transactions

What Is a POS Point of Sale Transaction 1024x512 1 Pinnacle Accounting & Advisory

Taxable Sales (10% GST)

GST applies to most sales of goods and services in Australia.

Examples:

  • professional services
  • retail sales
  • consulting fees

These should be coded as GST on Income.


GST-Free Sales

Some sales are GST-free, including:

  • most basic food
  • medical services
  • exports

GST-free does not mean “no reporting” — these amounts still appear on the BAS.


Input-Taxed Sales

The Hidden GST Trap Why Most Financial Services Are Input Taxed in Australia scaled 1 Pinnacle Accounting & Advisory

Input-taxed sales include:

  • residential rent
  • certain financial supplies

No GST is charged, and no GST credits can be claimed on related expenses. This is a common area of misunderstanding, especially for property investors and trusts.


GST Coding on Expense Transactions

GST on Expenses (Claimable)

Expenses that generally include GST:

  • office supplies
  • marketing and advertising
  • professional fees

Correct coding ensures GST credits are claimed.


GST-Free Expenses

Some expenses do not include GST, such as:

  • bank fees
  • government charges
  • certain medical expenses

These should not be coded as GST claimable.


Input-Taxed Related Expenses

If an expense relates to input-taxed income (e.g. residential rental property), GST credits cannot be claimed, even if GST appears on the invoice.

This is a common error we identify during BAS reviews.


GST Coding for Wages, Super, and Payroll

  • Wages and salaries – no GST
  • Superannuation – no GST
  • PAYG withholding – no GST

These items are often mistakenly coded with GST when payroll systems are not set up correctly.

Understanding payroll and reporting obligations helps avoid errors, as explained in
👉 What Are Employee Entitlements? A Guide for Australian Employers


GST Coding and BAS Reporting

Your GST coding directly feeds into your Business Activity Statement (BAS).

Incorrect coding leads to:

  • incorrect GST payable or refundable
  • amended BAS lodgements
  • ATO scrutiny

If you’re unsure how BAS works, read
👉 What Is a BAS (Business Activity Statement)?


GST Coding Errors and ATO Risk

The ATO uses data-matching and benchmarking to identify GST inconsistencies.

Red flags include:

  • unusually large GST refunds
  • fluctuating GST amounts
  • repeated BAS amendments

Poor GST coding is one of the most common triggers for reviews and audits, which is why professional oversight matters. This is covered further in
👉 ATO Audit Support for Businesses: What It Is and Why It Matters


How Good Bookkeeping Prevents GST Errors

Accurate GST coding relies on good bookkeeping processes, not just software.

Regular reviews ensure:

  • transactions are coded correctly
  • GST errors are identified early
  • BAS lodgements are accurate

This is why bookkeeping is foundational, as discussed in
👉 What Is Bookkeeping and How Your Accountant Can Help


How Your Accountant Helps With GST Coding

At Pinnacle Accounting & Advisory, we help businesses:

  • set up correct GST codes from day one
  • review GST treatment on complex transactions
  • identify and correct GST errors
  • ensure BAS accuracy
  • reduce ATO risk

This proactive approach prevents small errors from becoming expensive problems.


Final Thoughts

GST coding is not just a technical task — it directly affects:

  • tax payable
  • cash flow
  • compliance risk

When GST coding is done correctly, BAS lodgements are smoother, audits are less stressful, and business owners have greater confidence in their numbers.
What is GST coding?

GST coding is the process of assigning the correct GST treatment to business transactions so GST is reported accurately on the BAS.

What happens if GST is coded incorrectly?

Incorrect GST coding can lead to overpaid or underpaid GST, amended BAS lodgements, penalties, and ATO audits.

Do all expenses include GST?

No. Some expenses are GST-free or input-taxed, and GST credits cannot always be claimed even if GST appears on the invoice.

Can accounting software automatically fix GST coding?

No. Software relies on correct setup and user input. Regular review by an accountant is essential to ensure GST is coded correctly.

General Advice Disclaimer: The information in this article is general in nature and does not constitute personal financial, tax, or legal advice. Your individual circumstances will determine the most appropriate approach for you. Please consult a registered tax adviser or CPA before acting on anything in this article. Liability limited by a scheme approved under Professional Standards Legislation.

This article contains general advice only and does not take into account your specific circumstances. Please speak with a qualified accountant or tax adviser before making financial decisions.

Coding is only half the picture. The other half is timing, which is set by your GST accounting method. See GST cash vs accruals for how each method changes when the GST actually falls due.

Frequently Asked Questions

What is GST coding?

GST coding is assigning the correct GST treatment to each transaction in your accounting software, such as GST on income, GST on expenses, GST-free, or input-taxed. Correct coding ensures the GST on your BAS is accurate and that you claim only the credits you are entitled to.

What are the main GST codes?

The main treatments are GST (standard 10%), GST-free (such as basic food and some health and education), input-taxed (such as residential rent and financial supplies), and out-of-scope items. Coding each transaction correctly is essential for an accurate BAS.

What happens if I code GST incorrectly?

Incorrect GST coding leads to an inaccurate BAS, meaning you may overpay or underpay GST and may need to make corrections or amendments. Systematic miscoding can also draw ATO attention, so it is worth reviewing your coding regularly.

How do I make sure my GST coding is correct?

Set correct default GST treatments in your chart of accounts, check the GST on each transaction as you reconcile, and review the GST report before lodging your BAS. Having an accountant review your file periodically catches recurring coding errors.

7 Tax Strategies Every $500K+ Business Should Be Using

The legal strategies most established business owners never hear about — download the guide straight to your inbox.

Get the Guide →
Loading posts…

About Mina Baselyous

Mina Baselyous is a Chartered Tax Advisor (CTA), Certified Practising Accountant (CPA) and Registered Tax Agent based in Melbourne. He founded Pinnacle Accounting & Advisory to give small and medium business owners the proactive, strategic advice most accountants never offer. Read Mina’s full profile and credentials.

LinkedIn  |  Instagram

Read more
Family Trust Blog banner Pinnacle Accounting & Advisory

Important Considerations for a Family Trust in Australia

A family trust (also known as a discretionary trust) is a commonly used structure in Australia for asset protection, tax planning, and managing family or business wealth. While flexible and powerful, family trusts are also complex and require careful ongoing management.

A family trust in australia is a commonly used structure in Australia for asset protection, tax planning, and managing family or business wealth.

Understanding how a family trust in australia operates can prevent many common issues.

Setting up a family trust in australia involves crucial decisions that should be made carefully.

Many of the problems we see with family trusts arise not from poor intentions, but from a lack of understanding of how trusts actually operate and how ATO rules apply.

This article outlines the key considerations trustees and beneficiaries should understand when operating a family trust in Australia. This article is about how a family trust is run. If you are weighing up whether to have one at all, start with our guide to family trust benefits and the traps nobody mentions.

The importance of a family trust in australia cannot be overstated for effective wealth management.


What Is the Trust Deed?

Understanding Family Trust in Australia

what is a trust deed in south africa 0 Pinnacle Accounting & Advisory
what is a trust deed in south africa,”0

The trust deed is the foundational legal document of a family trust.

It governs:

  • how the trust operates
  • who controls the trust
  • who can benefit
  • how income and capital can be distributed

Every action taken by the trustee must comply with the trust deed. If a distribution or decision falls outside the deed, it may be invalid and expose the trust to adverse tax outcomes.

Before making any trust decision, the deed should always be reviewed.

All trustees should familiarize themselves with the family trust in australia to ensure compliance.


The role of the appointor is vital in a family trust in australia.

When managing a family trust in australia, the appointor holds significant power.

Who Is the Appointor?

The appointor is one of the most powerful roles within a family trust.

This authority over a family trust in australia necessitates a clear understanding of the trust’s operations.

Typically, the appointor has the authority to:

  • appoint or remove the trustee
  • influence control of the trust over time

This role is particularly important for succession planning, as many deeds specify who becomes appointor on death or incapacity.

Because of its importance, appointors, including single vs multiple appointors and successor appointors will be covered in a separate dedicated article.


Creating a trust resolution minute is essential for a family trust in australia.

What Is a Resolution Minute?

Failing to prepare a resolution minute can jeopardize a family trust in australia’s tax standing.

A trust resolution minute (also known as a trust distribution minute) records the trustee’s decision on how trust income is allocated to beneficiaries for a financial year.

This is a critical compliance requirement.

If a valid resolution minute is not prepared on or before 30 June, trust income may be taxed at the highest marginal tax rate.

Income splitting strategies can enhance the benefits of a family trust in australia.

Understanding the implications of income splitting in a family trust in australia is crucial.

This issue is explained in detail in
👉 Trust Distribution Minutes: Why They Matter and What Trustees Must Do Before 30 June


What Is Income Splitting?

Income splitting allows trustees to distribute trust income across different beneficiaries based on their tax positions.

Common strategies include distributing income to:

  • adult family members on lower marginal tax rates
  • a company beneficiary
  • other eligible entities

While legal when done correctly, income splitting must comply with the trust deed and tax law. Poor execution can lead to ATO scrutiny.

Income streaming can be highly beneficial for a family trust in australia.

Understanding your numbers and tax position before distributing income is essential, as discussed in
👉 The Truth About Sales & Accounting: Why Knowing Your Numbers Is the Ultimate Business Strategy

Watch the video:


What Is Income Streaming?

images 5 Pinnacle Accounting & Advisory

Income streaming allows specific types of income to be directed to specific beneficiaries.

For example:

  • capital gains to beneficiaries with capital losses
  • franked dividends to beneficiaries who can utilise franking credits

Income streaming is only effective if:

  • the trust deed permits it
  • distributions are documented correctly

This is a technical area that requires careful planning.


Who Is the Settlor and What Do They Do?

The settlor is the person who establishes the trust by contributing the initial settlement sum.

Establishing the role of the settlor is vital in a family trust in australia.

Key points:

  • the settlor should not be a beneficiary
  • the settlor should not control the trust
  • their role typically ends once the trust is established

Incorrectly appointing a settlor can compromise the integrity of the trust.


Who Can Be a Beneficiary?

Who can receive distributions depends entirely on the trust deed.

Beneficiaries may include:

  • individuals
  • companies
  • other trusts

Is your family trust set up and run the right way?

At Pinnacle Accounting & Advisory we help Melbourne business owners structure and manage trusts for tax efficiency and asset protection. Book a consultation with Mina to find out where you stand.

Book a Consultation

Determining who can be a beneficiary in a family trust in australia requires careful consideration.

However, not all beneficiaries are suitable in every situation, and eligibility must always be confirmed before making distributions.

This topic — including individual vs company vs trust beneficiaries — will be covered in a separate video and article.


Section 100A: A Growing Risk Area

Section 100A is an ATO anti-avoidance provision that targets certain trust arrangements, particularly where beneficiaries are assessed on income they do not actually benefit from.

This is an area of increasing ATO focus and enforcement and will be covered in a separate detailed blog.


Test Individual and Family Trust Elections

Section 100A poses an increased risk for a family trust in australia that needs to be monitored.

Some trusts make elections that impact:

  • loss utilisation
  • distribution flexibility
  • future tax outcomes

Test individuals and family trust elections are complex and can have long-term consequences. This topic will be addressed in a separate in-depth article.


Test individuals and family trust elections can significantly impact a family trust in australia.

Life of a Trust: 40 or 80 Years

family trust 2 Pinnacle Accounting & Advisory

Family trusts do not last forever.

Most trust deeds include a vesting date, commonly:

  • 40 years
  • 80 years

When a trust vests:

  • assets may need to be distributed
  • capital gains tax may arise
  • control of the trust changes

Understanding the life cycle of a trust is essential for long-term planning.

Understanding the lifespan of a family trust in australia is critical for planning.


Why Strong Systems Matter for Trusts

Trust compliance is not just about legal documents — it’s also about financial discipline.

Poor systems often result in:

  • incorrect use of trust funds
  • cash flow issues
  • compliance breaches

Strong financial separation and systems help reduce these risks, as outlined in
👉 The 6 Bank Accounts Every Business Owner Needs

Watch the video:


Trusts and Company Beneficiaries

Where trust income is distributed to a company beneficiary, trustees must be careful to avoid Division 7A issues if funds are not handled correctly.

This interaction is one of the most common trust mistakes and is explained in
👉 Top 5 Division 7A Loan Traps to Avoid


Developing strong systems is essential for maintaining a family trust in australia.

Final Thoughts

A family trust can be an excellent structure when used correctly — but it is not a set-and-forget solution.

Trustees must understand:

  • how the trust deed operates
  • who controls the trust
  • how distributions work
  • where ATO risk arises

With proper advice, documentation, and systems, a family trust can deliver long-term benefits instead of long-term problems.

To understand how a family trust fits within the full range of Australian business structures — and how to choose between a trust, company, or combined approach — see our complete guide to business structures in Australia.


Disclaimer

This article is general information only and does not constitute tax or legal advice. Family trust outcomes depend on individual circumstances. Always seek advice from a qualified accountant or tax agent.

Trustees must navigate Division 7A issues within a family trust in australia carefully.

Ultimately, a family trust in australia can offer significant benefits when managed correctly.

Frequently Asked Questions

What should I consider before setting up a family trust?

Consider who will be the appointor and trustee, whether to use a corporate trustee, who the beneficiaries are, the stamp duty and setup costs, and how distributions will work each year. A trust is powerful but must genuinely suit your family and business circumstances.

What are the ongoing obligations of a family trust?

Each year the trustee must decide and document distributions before 30 June, prepare financial statements and a tax return, and keep proper records. Missing the annual distribution resolution can lead to the trustee being taxed on the income at the top marginal rate.

What is section 100A and why does it matter?

Section 100A is an anti-avoidance rule the ATO applies where trust income is distributed to a beneficiary on paper but the real benefit goes to someone else. It means adult-child and family distributions must be genuine and properly documented to be effective.

Can a family trust protect my assets?

Yes, to a degree. Because assets are held by the trustee rather than by individuals, they can be better protected from personal creditors, and a corporate trustee strengthens this. Protection is not absolute, though, and depends on how the trust is set up and run.

This article contains general advice only and does not take into account your specific circumstances. Please speak with a qualified accountant or tax adviser before making financial decisions.

Loading posts…

About Mina Baselyous

Mina Baselyous is a Chartered Tax Advisor (CTA), Certified Practising Accountant (CPA) and Registered Tax Agent based in Melbourne. He founded Pinnacle Accounting & Advisory to give small and medium business owners the proactive, strategic advice most accountants never offer. Read Mina’s full profile and credentials.

LinkedIn  |  Instagram

Read more
Payroll blog banner Pinnacle Accounting & Advisory

Payroll: Ensuring Staff Are Paid Correctly in Australia

Payroll in Australia involves paying employees correctly, withholding PAYG tax, paying superannuation, and reporting to the ATO through Single Touch Payroll. Employers must apply the correct award rates and entitlements, meet super guarantee obligations, and keep accurate records. Getting payroll right is both a compliance requirement and key to staff trust.

Payroll is one of the most critical responsibilities for any business that employs staff. Ensuring employees are compensated correctly is not just about meeting payday expectations; it’s about legal compliance, cash flow management, employee trust, and avoiding ATO and Fair Work penalties.

Many issues arise not from intentional wrongdoing, but from poor systems, incorrect setup, or lack of ongoing review.

This article explains why payroll accuracy matters, what employers must get right, and how professional support helps businesses stay compliant and confident.


Why Correct Payroll Matters

images 12 Pinnacle Accounting & Advisory

Accurate payroll ensures:

  • employees are paid the correct wages
  • superannuation is calculated and paid correctly
  • PAYG withholding is accurate
  • leave entitlements are tracked properly

Errors can lead to:

  • underpayments and back pay
  • penalties and interest
  • employee disputes
  • ATO or Fair Work audits

Compliance is non-negotiable for Australian businesses.


Key Payroll Components Employers Must Get Right

Correct Pay Rates and Awards

images 13 Pinnacle Accounting & Advisory

Employees must be paid:

  • in line with their award or enterprise agreement
  • at or above minimum wage
  • for correct hours worked, including overtime

Incorrect award interpretation is one of the most common payroll compliance issues.


Superannuation Guarantee

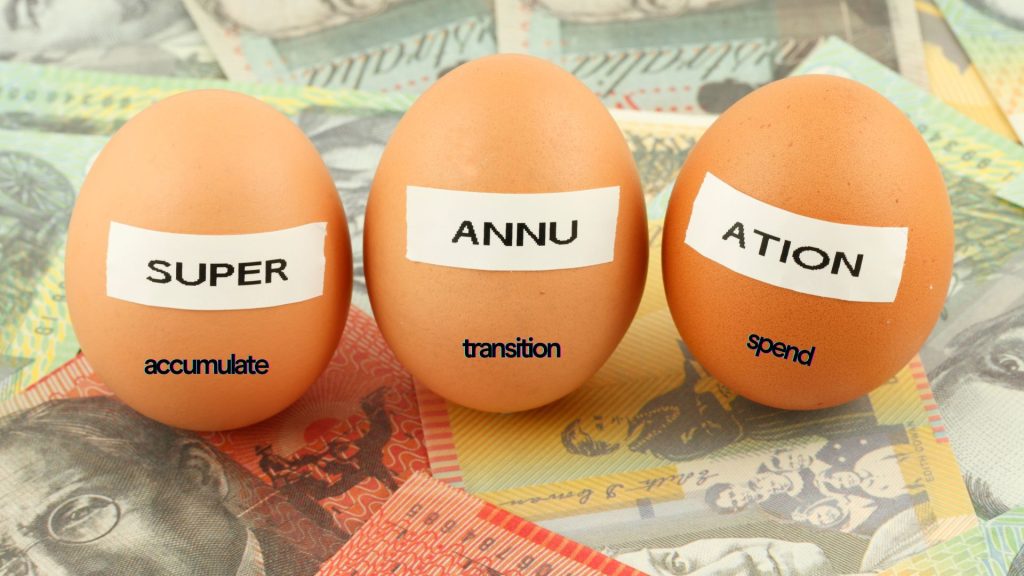
66d105204595850ce1a93789 65646a035bc00e5809b2fd7b superannuation phases financial education Pinnacle Accounting & Advisory

Superannuation is a mandatory employee entitlement.

Employers must:

  • calculate super at the correct rate
  • pay it by the quarterly due dates
  • ensure payments are reported accurately

Late super payments are not tax deductible and may trigger penalties. Planning for super is essential, as discussed in
👉 The 6 Bank Accounts Every Business Owner Needs

Or watch the video:


PAYG Withholding

images 14 Pinnacle Accounting & Advisory

Employers must withhold tax from employee wages and report it correctly to the ATO.

Incorrect PAYG withholding often leads to:

  • unexpected tax liabilities
  • amended BAS or IAS lodgements
  • ATO scrutiny

Employers must ensure that they are aware of their obligations in managing staff compensation.

Understanding reporting obligations helps avoid errors, as explained in
👉 What Is a BAS (Business Activity Statement)?


Leave Accruals and Entitlements

How To Calculate Leave Accrual For Your Employees Pinnacle Accounting & Advisory

Payroll systems must correctly track:

  • annual leave
  • personal/carer’s leave
  • long service leave

Leave accruals represent future liabilities and should be reviewed regularly.

Employer obligations are explained further in
👉 What Are Employee Entitlements? A Guide for Australian Employers


At Pinnacle Accounting & Advisory, we help businesses:

Payroll errors are a major focus area for:

  • the ATO
  • the Fair Work Ombudsman

Common payroll red flags include:

  • unpaid or late superannuation
  • inconsistent wage reporting
  • incorrect PAYG withholding
  • poor payroll recordkeeping

These issues often trigger audits or reviews, which is why professional support matters. Learn more in
👉 ATO Audit Support for Businesses: What It Is and Why It Matters


Payroll and Cash Flow Planning

Payroll represents one of the largest and most regular cash outflows for businesses.

Poor payroll planning can lead to:

  • cash shortages
  • missed tax obligations
  • rushed or incorrect payments

Businesses that understand their numbers and review payroll costs regularly are better positioned to grow sustainably, as discussed in
👉 The Truth About Sales & Accounting: Why Knowing Your Numbers Is the Ultimate Business Strategy

Watch the video:


Some of the most common payroll mistakes include:

  • misclassifying employees as contractors
  • missing superannuation deadlines
  • incorrect award rates
  • failing to track leave properly
  • relying on software without review

Payroll software helps — but it does not replace professional oversight.


At Pinnacle Accounting & Advisory, we help businesses:

  • set up payroll systems correctly
  • review pay rates and entitlements
  • ensure superannuation compliance
  • align payroll with BAS and IAS reporting
  • identify and fix errors early

This proactive approach reduces compliance risk and protects both the business and its employees.


Payroll is an important responsibility for any business, requiring:

Payroll requires:

  • regular review
  • updated award knowledge
  • accurate recordkeeping
  • alignment with tax reporting

Businesses that treat payroll as an ongoing process — not a once-off setup — experience fewer disputes and far less stress.


Final Thoughts

Ensuring staff are compensated correctly is one of the most important responsibilities of running a business.

Accurate payroll:

  • protects cash flow

With the right systems and professional guidance, payroll becomes a strength rather than a risk.

Why is payroll accuracy important for businesses?

Payroll accuracy ensures employees are paid correctly, superannuation is compliant, and ATO and Fair Work penalties are avoided.

What happens if payroll is done incorrectly?

Payroll errors can result in underpayments, penalties, interest, audits, and employee disputes.

Is payroll software enough to ensure compliance?

No. Payroll software assists with processing, but employers must still ensure correct setup, award interpretation, and ongoing review.

How can an accountant help with payroll?

An accountant ensures payroll systems are set up correctly, compliance obligations are met, and errors are identified before they become costly.

Loading posts…

General Advice Disclaimer: The information in this article is general in nature and does not constitute personal financial, tax, or legal advice. Your individual circumstances will determine the most appropriate approach for you. Please consult a registered tax adviser or CPA before acting on anything in this article. Liability limited by a scheme approved under Professional Standards Legislation.

Frequently Asked Questions

What does running payroll in Australia involve?

Payroll involves calculating employees’ pay and entitlements, withholding PAYG tax, calculating and paying superannuation, reporting each pay run to the ATO through Single Touch Payroll, and keeping accurate records. Employers must also apply the correct award or agreement rates.

What is Single Touch Payroll?

Single Touch Payroll (STP) is the system through which employers report salaries, PAYG withholding and super to the ATO each time they run payroll. Reporting happens as part of every pay run, so the ATO has up-to-date information on wages and withholding.

How much super do I pay employees?

Super guarantee is 12% of ordinary time earnings for the 2025-26 year, paid at least quarterly by the due dates, or under payday super from 1 July 2026, at the same time as wages. It must reach the employee’s fund by the due date.

What payroll records must employers keep?

Employers must keep records of pay, hours, leave, super and tax withheld for seven years. Both Fair Work and the ATO require accurate records, and penalties apply for missing or false records, so reliable payroll software is strongly recommended.

This article contains general advice only and does not take into account your specific circumstances. Please speak with a qualified accountant or tax adviser before making financial decisions.

Loading posts…

About Mina Baselyous

Mina Baselyous is a Chartered Tax Advisor (CTA), Certified Practising Accountant (CPA) and Registered Tax Agent based in Melbourne. He founded Pinnacle Accounting & Advisory to give small and medium business owners the proactive, strategic advice most accountants never offer. Read Mina’s full profile and credentials.

LinkedIn  |  Instagram

Read more
BAS Blog Banner 1 Pinnacle Accounting & Advisory

What Is a BAS (Business Activity Statement)?

If you run a business in Australia, chances are you’ve heard of a BAS (Business Activity Statement), but many business owners still feel unsure about what it actually is, why it matters, and how to manage it properly.

Understanding your Business Activity Statement is crucial for every business owner.

The Business Activity Statement helps ensure your taxes are correctly calculated.

A BAS is one of the ATO’s primary tools for collecting taxes from businesses. Getting it right is critical for cash flow management, compliance, and avoiding penalties.

In this article, we explain what a BAS is, what it includes, who needs to lodge one, and how good systems and advice make BAS obligations far easier to manage.


Every Australian business must submit a Business Activity Statement for tax purposes.

What Is a Business Activity Statement (BAS)?

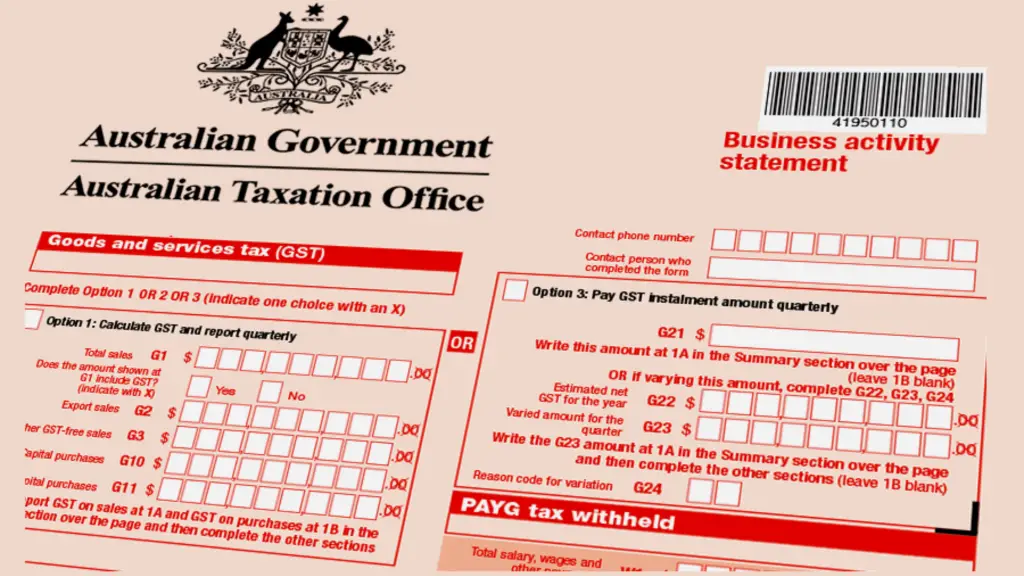
Business Activity Statement BAS Sample Lodgement Pinnacle Accounting & Advisory

A Business Activity Statement (BAS) is a form businesses lodge with the Australian Taxation Office (ATO) to report and pay certain taxes.

Depending on your business, a BAS may include:

  • Goods and Services Tax (GST)
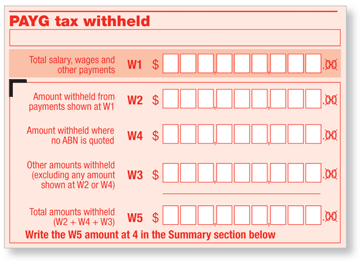
  • Pay As You Go (PAYG) withholding
  • PAYG income tax instalments
  • Fringe Benefits Tax (FBT) instalments

The ATO uses your BAS to reconcile what tax you’ve collected or withheld on its behalf.


The Business Activity Statement plays a key role in your business reporting.

Who Needs to Lodge a BAS?

Each Business Activity Statement lodgement represents a commitment to compliance.

Learning about your Business Activity Statement can save you time and money.

You generally need to lodge a BAS if your business is:

  • registered for GST, or
  • required to withhold tax from employees or contractors

This applies to:

  • sole traders
  • partnerships
  • companies
  • trusts

Even if no activity occurred during the period, a nil BAS may still be required.


How Often Is a BAS Lodged?

BAS lodgement frequency depends on your business size and ATO classification:

  • Monthly – usually larger businesses
  • Quarterly – most small businesses
  • Annually – limited cases

Understanding and planning for these deadlines is essential, particularly around busy periods like January. We cover this in detail in
👉 January BAS Deadlines and ATO Obligations Every Business Owner Should Know


Correctly filing your Business Activity Statement is essential for maintaining good standing with the ATO.

What Taxes Are Reported on a BAS?

1659934014 taxes Pinnacle Accounting & Advisory

GST

If registered for GST, your BAS reports:

  • GST collected on sales
  • GST paid on business expenses

The difference determines whether you owe the ATO or receive a refund.


PAYG Withholding

Consider consulting an expert for your Business Activity Statement submissions.

Reviewing your Business Activity Statement helps avoid costly mistakes.

If you have employees, you must withhold tax from wages and report this on your BAS.


Each item in your Business Activity Statement needs careful consideration.

PAYG Instalments

The Business Activity Statement reflects your operational efficiency.

Many businesses also prepay income tax through PAYG instalments, which are reported and paid via the BAS.


FBT Instalments

Some businesses pay FBT instalments through their BAS rather than in a separate return.


Why BAS Management Is So Important

Poor BAS management is one of the most common causes of:

  • cash flow stress
  • ATO penalties and interest
  • audit activity

Problems often arise when businesses:

  • use GST funds for operating expenses
  • fall behind on bookkeeping
  • don’t separate tax money from business cash

This is why strong systems are essential, particularly proper account separation, as outlined in
👉 The 6 Bank Accounts Every Business Owner Needs

Not sure if you are getting your BAS right?

At Pinnacle Accounting & Advisory we help Melbourne business owners get your BAS prepared and lodged accurately, on time. Book a consultation with Mina to find out where you stand.

Book a Consultation

Or watch the video:


BAS and ATO Audit Risk

BAS errors, inconsistencies, or unusual claims can trigger ATO reviews or audits.

Common red flags include:

  • unusually large GST refunds
  • inconsistent BAS and tax return data
  • late or frequent amended BAS lodgements

If selected for review, having clean records and professional support makes the process significantly easier. We explain this further in
👉 ATO Audit Support for Businesses: What It Is and Why It Matters


BAS and Cash Flow Planning

A BAS is not just a compliance document — it’s also a cash flow event.

Failing to plan for BAS payments often leads to:

  • scrambling for funds
  • payment plans with the ATO
  • compounding stress

Understanding your numbers and reviewing them regularly allows you to plan BAS obligations instead of reacting to them. This principle is discussed in
👉 The Truth About Sales & Accounting: Why Knowing Your Numbers Is the Ultimate Business Strategy

Or watch the video:


Common BAS Mistakes to Avoid

Some of the most common BAS mistakes include:

  • claiming GST on non-creditable expenses
  • missing lodgement deadlines
  • reporting incorrect sales figures
  • not reconciling bank accounts before lodgement

These issues are almost always preventable with consistent bookkeeping and professional oversight.


How Professional BAS Support Helps

Working with an accountant or BAS agent helps ensure:

  • accurate GST reporting
  • correct PAYG calculations
  • timely lodgements
  • reduced audit and penalty risk

It also frees business owners to focus on growth instead of compliance stress.


Final Thoughts

A BAS is a core part of running a business in Australia — not just a form to lodge, but a reflection of your business systems and financial discipline.

When managed correctly, a BAS:

  • supports cash flow planning
  • reduces ATO risk
  • improves financial clarity

When ignored or rushed, it becomes a source of ongoing stress.

Understanding your BAS obligations — and setting up the right systems early — is one of the smartest moves any business owner can make.


Disclaimer

Careful management of your Business Activity Statement is vital for your business health.

This article is general information only and does not constitute tax or financial advice. BAS obligations vary depending on individual circumstances. Always seek advice from a qualified accountant or BAS agent.

Don’t underestimate the importance of your Business Activity Statement in tax planning.

Ultimately, your Business Activity Statement is a key indicator of financial health.

Mastering your Business Activity Statement can lead to better financial management.

What is a BAS used for in Australia?

A BAS is used by the ATO to collect and reconcile business taxes such as GST, PAYG withholding, PAYG instalments, and FBT instalments. It allows businesses to report and pay these obligations on a regular basis.

Do I need to lodge a BAS if my business has no activity?

Yes. If your business is registered for GST or required to lodge a BAS, you may still need to submit a nil BAS even if there was no activity during the reporting period.

How often do I need to lodge a BAS?

BAS lodgement frequency depends on your business size and ATO classification. Most small businesses lodge quarterly, while larger businesses may be required to lodge monthly.

What happens if I lodge my BAS late?

Late BAS lodgements can result in ATO penalties, interest charges, and increased compliance scrutiny. Repeated late lodgements may also limit future payment plan options.

This article contains general advice only and does not take into account your specific circumstances. Please speak with a qualified accountant or tax adviser before making financial decisions.

One decision that changes every BAS you ever lodge is whether you report GST on a cash or an accruals basis. Our guide to GST cash vs accruals sets out who can choose, and what each method does to your cash flow.

Loading posts…

About Mina Baselyous

Mina Baselyous is a Chartered Tax Advisor (CTA), Certified Practising Accountant (CPA) and Registered Tax Agent based in Melbourne. He founded Pinnacle Accounting & Advisory to give small and medium business owners the proactive, strategic advice most accountants never offer. Read Mina’s full profile and credentials.

LinkedIn  |  Instagram

Read more
Tax Depreciation Blog Banner 3 Pinnacle Accounting & Advisory

Tax Depreciation 2026 Explained: How It Works, Why It Matters, and How Australians Miss Out

Tax depreciation lets businesses and property investors deduct the declining value of assets over their effective life, spreading the cost as a deduction across the years the asset is used. For property investors especially, a depreciation schedule often uncovers thousands in deductions that are otherwise missed each year.

Tax depreciation is one of the most powerful and most commonly overlooked, deductions available to Australian taxpayers, particularly property investors and business owners.

Each year, many Australians overpay tax not because they’re ineligible for deductions, but because they don’t fully understand how depreciation works, what can be claimed, or when a depreciation schedule is required.

This article explains tax depreciation in Australia, how it works, why it matters, and how it should be used strategically, especially as part of mid-year and EOFY tax planning.


What Is Tax Depreciation?

tax depreciation 1 Pinnacle Accounting & Advisory

Tax depreciation allows you to claim a deduction for the decline in value of eligible assets over time.

Rather than claiming the full cost of an asset upfront, the ATO allows deductions to be spread over the asset’s effective life, reflecting wear and tear or obsolescence.

Importantly, depreciation is a non-cash deduction, you don’t need to spend money each year to claim it, yet it still reduces your taxable income.


Why Tax Depreciation Matters

When claimed correctly, depreciation can:

  • reduce taxable income
  • increase tax refunds
  • improve after-tax cash flow
  • make investments more tax-effective

Because depreciation does not affect your bank balance, it improves cash flow without impacting day-to-day liquidity. Over time, this can significantly influence long-term wealth and borrowing capacity.

This is the same principle discussed in The Truth About Sales & Accounting: Why Knowing Your Numbers Is the Ultimate Business Strategy, understanding how numbers work behind the scenes leads to better strategic decisions.


What Can Be Depreciated?

Depreciation in Australia generally falls into two categories:

🔹 Plant & Equipment (Division 40)

These are assets that can wear out or be replaced, such as:

  • appliances
  • carpets and flooring
  • air-conditioning units
  • hot water systems
  • security systems

Eligibility depends on asset type, purchase date, and how the property is used.


🔹 Capital Works (Division 43)

Capital works typically include structural elements of a building, such as:

  • walls, floors, and roofs
  • fixed cabinetry
  • bathrooms and kitchens
  • original construction costs

Capital works are commonly depreciated at 2.5% per year over 40 years, subject to eligibility rules.


Depreciation for Investment Properties

images 8 Pinnacle Accounting & Advisory

For Australian property investors, depreciation is most commonly claimed on investment properties.

To claim depreciation correctly, investors generally require an ATO-compliant depreciation schedule prepared by a qualified quantity surveyor.

A depreciation schedule:

  • identifies eligible assets
  • calculates annual deductions
  • complies with ATO requirements
  • supports claims if reviewed by the ATO

Without a schedule, many investors either under-claim or don’t claim depreciation at all.

This is why depreciation works best when combined with strong financial systems, as explained in The 6 Bank Accounts Every Business Owner Needs

Watch the complete video:


Depreciation as a Mid-Year Tax Planning Strategy

images 9 Pinnacle Accounting & Advisory

One of the biggest mistakes investors make is treating depreciation as something to think about after 30 June.

In reality, depreciation should be reviewed mid-year, alongside other tax planning strategies, to understand how it will impact your overall tax position.

Are you claiming all the depreciation you are entitled to?

At Pinnacle Accounting & Advisory we help Melbourne business owners make sure you claim every depreciation deduction available. Book a consultation with Mina to find out where you stand.

Book a Consultation

As we explain in Mid-Year Tax Planning 2026: What to Do Now to Maximise Your EOFY Tax Outcome, reviewing deductions early gives you time to:

  • forecast taxable income
  • manage cash flow
  • avoid rushed EOFY decisions

Depreciation often forms a significant portion of total deductions, which is why it should be factored into tax planning well before EOFY.


New vs Established Properties

Both new and established properties may be eligible for depreciation, though the rules differ.

  • Newer properties typically generate higher depreciation deductions
  • Established properties may still qualify, particularly for capital works

Even if a property was built many years ago, depreciation may still be available if construction occurred after relevant cutoff dates.


Common Depreciation Mistakes

Some of the most common issues we see include:

  • no depreciation schedule in place
  • assuming older properties have no depreciation
  • relying on estimates rather than a quantity surveyor
  • incorrect treatment of renovations
  • failing to integrate depreciation into tax planning

These mistakes often result in missed deductions and unnecessary tax over multiple years.


Depreciation, Cash Flow, and EOFY Outcomes

Because depreciation reduces taxable income without reducing cash, it can:

  • improve annual cash flow
  • reduce tax withheld during the year
  • strengthen EOFY tax outcomes

When depreciation is factored into mid-year tax planning, it provides clearer visibility over what your final tax position is likely to be, reducing surprises after 30 June.


Depreciation and ATO Scrutiny

With increased ATO focus on property and deduction claims, accuracy matters.

The ATO expects:

  • correct asset classification
  • appropriate effective lives
  • supporting documentation

An ATO-compliant depreciation schedule helps support claims and reduces audit risk.

Watch:


Final Thoughts

Tax depreciation is not just a technical deduction, it is a strategic tax planning tool.

When understood and applied correctly, and reviewed as part of mid-year and EOFY tax planning, depreciation can:

  • reduce tax
  • improve cash flow
  • strengthen long-term investment outcomes

Ignoring depreciation, or leaving it until tax time, often means paying more tax than necessary.


Depreciation on cars has its own cap, and that cap follows the asset all the way to disposal. See selling a car above the car limit for how the balancing adjustment is calculated when the car limit applied.

General Advice Disclaimer

The information in this article is general in nature and does not constitute personal financial, tax, or legal advice. It has been prepared without taking into account your specific objectives, financial situation, or needs. Before acting on this information, you should consider its appropriateness to your circumstances and seek independent advice from a qualified professional. Pinnacle Accounting & Advisory is a registered tax agent. Liability limited by a scheme approved under Professional Standards Legislation.

What is tax depreciation in Australia?

Tax depreciation in Australia allows taxpayers to claim a deduction for the decline in value of eligible assets over time. It applies to assets used to produce assessable income, including investment properties, and helps reduce taxable income without requiring additional cash outlay.

Do I need a depreciation schedule to claim depreciation on an investment property?

In most cases, yes. An ATO-compliant depreciation schedule prepared by a qualified quantity surveyor is required to accurately calculate and support depreciation claims for an investment property. Without a schedule, many investors underclaim or miss depreciation altogether.

Can depreciation be used as part of mid-year tax planning?

Yes. Depreciation should be reviewed as part of mid-year tax planning to forecast taxable income, manage cash flow, and improve EOFY tax outcomes. Leaving depreciation until after 30 June often limits planning opportunities.

Do older properties still qualify for tax depreciation?

Yes. Older properties may still qualify for tax depreciation, particularly for capital works deductions. Even if a property was built many years ago, depreciation may still be available depending on construction dates and eligibility rules.

This article contains general advice only and does not take into account your specific circumstances. Please speak with a qualified accountant or tax adviser before making financial decisions.

Loading posts…

About Mina Baselyous

Mina Baselyous is a Chartered Tax Advisor (CTA), Certified Practising Accountant (CPA) and Registered Tax Agent based in Melbourne. He founded Pinnacle Accounting & Advisory to give small and medium business owners the proactive, strategic advice most accountants never offer. Read Mina’s full profile and credentials.

LinkedIn  |  Instagram

Read more
Trust Distribution Minutes Blog Banner 1 Pinnacle Accounting & Advisory

Trust Distribution Minutes: Why They Matter in 2026 and What Trustees Must Do Before 30 June

Trust distribution minutes are the written resolutions a trustee signs before 30 June each year to validly distribute a discretionary trust’s income to beneficiaries. Without a valid, signed resolution by year end, the ATO can tax the trustee on the whole of the trust’s income at 47%, so the minutes directly protect your tax position. Well-drafted minutes also help defend distributions against Section 100A.

For trustees of discretionary (family) trusts, trust distribution minutes are one of the most important — and most commonly missed, annual compliance requirements.

Every year, we see trustees unintentionally expose themselves to unnecessary tax simply because a distribution decision was not properly documented before 30 June.

In this article, we explain what trust distribution minutes are, why they are critical for 2026 tax compliance, what happens if you miss the deadline, and how trustees can protect themselves with the right processes and advice.

If you are still deciding whether a family trust is the right structure for your business, our complete guide to business structures in Australia covers all four main structures and helps you identify the best fit for your situation.


What Is a Trust Distribution Minute?

A trust distribution minute (also known as a trust distribution resolution) is a formal written record of the trustee’s decision on how the trust’s income for the financial year will be distributed to beneficiaries.

The minute should clearly state:

  • which beneficiaries are entitled to trust income
  • the amount or percentage allocated to each beneficiary
  • the date the decision was made
  • confirmation that the trustee has exercised discretion in accordance with the trust deed

Most importantly, the distribution minute must be prepared and signed on or before 30 June of the relevant financial year.


Why Trust Distribution Minutes Matter for Tax in 2026

Under Australian tax law, trust income is taxed based on who is presently entitled to that income at year end.

If a valid distribution minute is not in place by 30 June:

  • beneficiaries are not considered presently entitled
  • the trust income may be taxed to the trustee
  • tax may apply at the highest marginal tax rate

This outcome often surprises trustees who believed they could “sort it out later” when the tax return is prepared. Unfortunately, intentions after 30 June do not count.


Common Mistakes Trustees Make

Some of the most common issues we see include:

  • preparing distribution minutes after 30 June
  • backdating documents (which is not accepted by the ATO)
  • distributing income to ineligible beneficiaries
  • failing to follow the trust deed
  • ignoring how distributions interact with company beneficiaries

These mistakes often result from DIY trust administration without professional guidance.

Many of these issues could be avoided by having better financial visibility and planning throughout the year — a concept discussed in The Truth About Sales & Accounting: Why Knowing Your Numbers Is the Ultimate Business Strategy

Watch The Video:


Trusts, Company Beneficiaries, and Division 7A

Where trust income is distributed to a company beneficiary, additional care is required.

Leaving the distribution unpaid is no longer the problem it once was. In Commissioner of Taxation v Bendel [2026] HCA 18, decided 10 June 2026, the High Court held that a private company which simply does nothing about its unpaid present entitlement does not provide financial accommodation under section 109D(3)(b), so the entitlement is not a Division 7A loan and no deemed dividend arises from it. If you are not sure what that balance on your trust’s books represents, start with our guide to unpaid present entitlements and how they work. The ATO accepted this in its Bendel Decision Impact Statement, published 26 June 2026.

What trustees must still watch, as at September 2026, is what happens to the money afterwards. Subdivision EA can still produce a deemed dividend where the trust pays, lends to, or forgives a debt of a shareholder of the company beneficiary or their associate while the entitlement remains outstanding, and section 100A still applies to reimbursement agreements. Accurate records of what was resolved and how each entitlement has been dealt with matter more than ever, because the character of the amount now turns on exactly those facts.

This interaction is complex and frequently misunderstood, which is why trustees should be familiar with Top 5 Division 7A Loan Traps to Avoid when using company beneficiaries.


Preparing Trust Distribution Minutes: Practical Steps

Review the Trust Deed

Ensure the deed:

  • allows discretionary distributions
  • identifies eligible beneficiaries
  • permits income streaming if required

The distribution minute must strictly comply with the deed.


Estimate Trust Income Before 30 June

While final figures may not be available, trustees should work with their accountant to estimate trust income before year end to make informed allocation decisions.


Decide on Tax-Effective Allocations

Consider:

  • beneficiaries’ marginal tax rates
  • use of corporate beneficiaries
  • streaming of capital gains or franked dividends

This step should never be rushed or left to late June.


Prepare and Sign the Minute on Time

The distribution minute must be:

  • dated correctly
  • signed by the trustee(s)
  • stored with trust records
  • completed on or before 30 June 2026

Electronic signatures are generally acceptable if properly documented.


What Happens If You Miss the Deadline?

If no valid trust distribution minute exists by 30 June:

  • trust income may be assessed to the trustee
  • tax can apply at up to 47% (including Medicare levy)
  • beneficiaries lose the intended tax benefit
  • ATO scrutiny risk increases

This outcome is entirely avoidable with proactive planning.


Trust Distribution Minutes Are an Annual Requirement

Even if:

  • income is low
  • no distributions are intended
  • the trust made a loss

A distribution decision should still be documented annually. Trust compliance is not optional and should be part of your year-round tax planning, not an EOFY scramble.


Final Thoughts

Trust distribution minutes are not just paperwork — they are a critical tax control mechanism.

Getting them right means:

  • protecting tax outcomes
  • avoiding trustee-level tax
  • reducing audit and compliance risk
  • ensuring your trust structure works as intended

If you operate a discretionary or family trust, preparing distribution minutes early, with professional oversight — is one of the smartest decisions you can make before 30 June 2026.

Frequently Asked Questions

What are trust distribution minutes?

Trust distribution minutes are the written resolutions a trustee signs each year recording how the trust’s income will be distributed among beneficiaries. They document the trustee’s decision, the amounts or percentages each beneficiary receives, and the date, and they are the evidence the ATO looks for that a valid distribution was made.

When must trust distribution minutes be signed?

The trustee must make and document the distribution resolution before the end of the financial year, that is by 30 June. Signing minutes after 30 June, or backdating them, is not acceptable and can invalidate the distribution, exposing the income to tax in the trustee’s hands at penalty rates.

What happens if a trust does not prepare distribution minutes?

If there is no valid resolution by 30 June, the trust’s income may not be effectively distributed, and the ATO can assess the trustee on the whole of the net income at the top marginal rate of 47%. Missing or defective minutes are one of the most expensive and avoidable trust mistakes.

Can trust distribution minutes be changed after 30 June?

No. Once the financial year has ended the distribution decision is locked in. Minutes cannot be validly altered or created after 30 June to change who received the income, which is why the resolution should be prepared and reviewed with your accountant before year end.

Do trust distribution minutes need to specify amounts?

The resolution must make beneficiaries presently entitled to the income, whether as specific dollar amounts, percentages, or a clear formula. Vague or default wording can be challenged, and streaming franked dividends or capital gains to particular beneficiaries needs specific, correctly worded clauses.

Want to pay less tax this financial year?

Download our guide: 7 Tax Strategies Every Business Owner Should Know — practical moves you can make right now.

Download the Free Guide

What is a trust distribution minute?

A trust distribution minute is a written record of the trustee’s decision on how trust income is allocated to beneficiaries for a financial year. It must be prepared and signed before 30 June.

What happens if a trust distribution minute is not prepared by 30 June?

If no valid minute exists, trust income may be taxed to the trustee at the highest marginal tax rate rather than to beneficiaries.

Do trust distribution minutes need to be prepared every year?

Yes. A distribution decision should be documented every financial year, even if income is low or no distributions are made.

Can trust distributions trigger Division 7A issues?

Yes, though not simply because the cash was left unpaid. Following Commissioner of Taxation v Bendel [2026] HCA 18, decided 10 June 2026, an unpaid present entitlement that a company beneficiary leaves outstanding is not a Division 7A loan. Subdivision EA can still apply where the trust pays money to, lends to, or forgives a debt of a shareholder of that company or their associate while the entitlement is outstanding.

Loading posts…

General Advice Disclaimer: The information in this article is general in nature and does not constitute personal financial, tax, or legal advice. Your individual circumstances will determine the most appropriate approach for you. Please consult a registered tax adviser or CPA before acting on anything in this article. Liability limited by a scheme approved under Professional Standards Legislation.

This article contains general advice only and does not take into account your specific circumstances. Please speak with a qualified accountant or tax adviser before making financial decisions.

Loading posts…

About Mina Baselyous

Mina Baselyous is a Chartered Tax Advisor (CTA), Certified Practising Accountant (CPA) and Registered Tax Agent based in Melbourne. He founded Pinnacle Accounting & Advisory to give small and medium business owners the proactive, strategic advice most accountants never offer. Read Mina’s full profile and credentials.

LinkedIn  |  Instagram

Read more
BAS Deadlines Blog Banner 1 Pinnacle Accounting & Advisory

BAS Deadlines and ATO Obligations Every Business Owner Should Know in January 2026

Business activity statement deadlines depend on your reporting cycle: quarterly BAS are generally due 28 October, 28 February, 28 April and 28 July, while monthly statements are due on the 21st. Meeting these deadlines, along with your PAYG and super obligations, keeps you compliant and avoids failure-to-lodge penalties.

January is a critical compliance month for Australian businesses. After the holiday period, many business owners return to work only to realize that BAS lodgements, PAYG instalments, superannuation obligations, and their ato obligations, including bas deadlines are due early in the new year. Missing these ATO deadlines can result in penalties, interest charges, and cash flow stress that set the tone for the rest of the year. It is crucial to manage these ato obligations effectively to ensure compliance with ATO obligations and to stay informed about bas deadlines.

This article outlines the key January BAS deadlines and ato obligations every business owner should be aware of and why addressing their ato obligations early matters to avoid complications in the compliance process related to their ato obligations.

Understanding the bas deadlines can prevent significant issues and ensure that your business remains compliant with ATO regulations.


Why January ATO Compliance Matters

Being aware of the upcoming bas deadlines is essential for maintaining smooth operations throughout the year.

January obligations often catch businesses off guard because:

  • trading slows over December
  • staff are on leave
  • records are not finalised before Christmas
  • cash flow is tighter after the holiday period

However, the ATO does not pause deadlines.

Failing to meet January compliance requirements can lead to:

For most businesses, familiarity with bas deadlines ensures timely submissions and helps in avoiding penalties.

  • late lodgement penalties
  • general interest charges (GIC)
  • loss of tax deductions (in some cases)
  • increased ATO scrutiny

Staying updated with bas deadlines can also help in better financial planning and management across the year.

Starting the year compliant puts your business in a far stronger position.

It is advisable to create reminders for employees about bas deadlines to maintain compliance.


January BAS Due Dates (What to Expect)

Business Activity Statement BAS Sample Lodgement Pinnacle Accounting & Advisory

Monthly BAS (December Period)

Businesses registered for monthly BAS generally need to lodge and pay their December BAS by 21 January.

This typically includes:

By adhering to bas deadlines, businesses can avoid complications and streamline their compliance processes.

  • GST
  • PAYG withholding

If you lodge through a registered tax or BAS agent, different lodgement arrangements may apply, but this should never be assumed without confirmation.


Consistent attention to bas deadlines can mitigate potential penalties and foster a positive relationship with the ATO.

Each January, understanding and managing bas deadlines is critical to ensure your business remains compliant with the ATO.

Quarterly BAS (December Quarter)

For businesses reporting quarterly, the December quarter BAS is commonly due in late January.

65faccc4f5d12243a687cfe2338ab83d scaled 1 Pinnacle Accounting & Advisory

This BAS may include:

  • GST
  • PAYG instalments (if applicable)

Exact due dates can vary depending on:

  • lodgement method
  • whether you use a registered agent

Confirming deadlines early avoids last-minute pressure.


PAYG Instalments Due in January

27808 5 Pinnacle Accounting & Advisory

Many business owners are also required to pay PAYG income tax instalments in January.

PAYG instalments are based on:

  • prior year tax
  • estimated current-year income

If cash flow has changed significantly, January is a good time to review whether PAYG instalments remain appropriate, rather than waiting until the instalment is already overdue.

Ignoring PAYG obligations can lead to compounding liabilities later in the year.


Superannuation Guarantee: A Critical January Deadline

download Pinnacle Accounting & Advisory

One of the most important January obligations is superannuation guarantee (SG).

December Quarter Superannuation

Superannuation for the December quarter is generally due by 28 January.

This applies to:

  • employees
  • eligible contractors

Struggling to keep on top of BAS and ATO deadlines?

At Pinnacle Accounting & Advisory we help Melbourne business owners never miss a lodgement deadline again. Book a consultation with Mina to find out where you stand.

Book a Consultation

⚠️ Important:
If superannuation is not paid by the due date:

  • it is not tax deductible
  • penalties and interest may apply
  • additional reporting obligations arise

Superannuation is one of the fastest ways businesses attract ATO attention when missed.


Common January Compliance Mistakes

Some of the most common issues we see in January include:

  • assuming deadlines were extended due to holidays
  • using GST or PAYG funds for operating expenses
  • incomplete bookkeeping delaying BAS preparation
  • forgetting superannuation payments
  • failing to review PAYG instalments when income has changed

These mistakes often result in avoidable penalties and unnecessary stress.

This is why proper cash flow structure is critical, as outlined in The 6 Bank Accounts Every Business Owner Needs


Why You Should Not Leave January Lodgements Until the Last Minute

Leaving BAS and ATO obligations until the deadline increases the risk of:

  • errors
  • cash flow shortfalls
  • missed deductions
  • late lodgement penalties

January is also when accountants and BAS agents are often dealing with:

  • multiple client deadlines
  • year-end reconciliations
  • compliance backlogs

Early preparation gives you options. Late action removes them.

Businesses that stay organised tend to make better decisions and avoid reactive behaviour — a concept explored in The Truth About Sales & Accounting: Why Knowing Your Numbers Is the Ultimate Business Strategy

In conclusion, understanding and managing bas deadlines is an essential part of maintaining compliance with ATO obligations throughout the year.

Watch the full video:


How January Compliance Impacts the Rest of the Year

January sets the compliance tone for the year ahead.

Businesses that:

  • stay up to date with BAS
  • pay superannuation on time
  • manage PAYG instalments proactively

are far less likely to face:

Proactive management of bas deadlines will save your business time and money in the long run.

  • ATO payment plans
  • penalty remissions
  • compliance stress later in the year

Good compliance habits early make tax planning and cash flow management far easier.


Final Thoughts

January is not just a “back to work” month, it is a key compliance checkpoint for Australian businesses.

Understanding January BAS due dates and ATO obligations helps you:

  • avoid penalties
  • protect cash flow
  • start the year confidently
  • reduce ATO risk

If you are unsure about your January obligations, now is the time to clarify them, not after a deadline has passed.


Disclaimer

This article is general information only and does not constitute tax or financial advice. ATO deadlines and obligations may vary depending on your circumstances. Always seek advice from a qualified accountant, BAS agent, or tax agent.

What BAS deadlines apply in January for Australian businesses?

In January, businesses may need to lodge and pay their December BAS. Monthly BAS reporters generally have a due date of 21 January, while quarterly reporters often have a late-January deadline. Exact dates can vary depending on lodgement method and whether a registered agent is used.

Is superannuation due in January?

Yes. Superannuation guarantee payments for the December quarter are generally due by 28 January. If superannuation is not paid by the due date, it is not tax deductible and penalties and interest may apply.

What happens if I miss a BAS or ATO deadline in January?

Missing a BAS or ATO deadline can result in late lodgement penalties, general interest charges, and increased ATO scrutiny. Repeated late lodgements may also impact future payment plan options.

Can PAYG instalments be reviewed in January?

Yes. January is a good time to review PAYG instalments, especially if business income has changed. Adjustments may be possible to better align instalments with current cash flow, but they should be reviewed carefully to avoid underpayment issues.

This article contains general advice only and does not take into account your specific circumstances. Please speak with a qualified accountant or tax adviser before making financial decisions.

Loading posts…

About Mina Baselyous

Mina Baselyous is a Chartered Tax Advisor (CTA), Certified Practising Accountant (CPA) and Registered Tax Agent based in Melbourne. He founded Pinnacle Accounting & Advisory to give small and medium business owners the proactive, strategic advice most accountants never offer. Read Mina’s full profile and credentials.

LinkedIn  |  Instagram

Read more
Mid Year Tax Planning Blog Banner 2 Pinnacle Accounting & Advisory

Mid-Year Tax Planning 2026: What to Do Now to Maximise Your EOFY Tax Outcome

Mid-year tax planning means reviewing your position well before 30 June so there is time to act. By assessing your likely profit, reviewing structure and distributions, timing income and expenses, and planning super contributions now, you can legally reduce your tax rather than discovering the bill when it is too late to change it.

For many Australians, tax planning only becomes a priority in June, when the financial year is almost over and most opportunities have already passed.

In reality, mid-year tax planning is where the biggest gains are made.

January marks the halfway point of the financial year and is an ideal time for individuals and business owners to step back, assess their current tax position, and make informed decisions that can significantly improve their end-of-financial-year (EOFY) tax outcome.

This article explains why proactive mid-year tax planning matters, and outlines practical EOFY tax strategies you can still implement if you act early.


Why Mid-Year Tax Planning Is So Important

Mid-year tax planning is not about finding loopholes or aggressive strategies. It’s about timing, preparation, and visibility.

Planning early allows you to:

  • Identify potential tax issues before they become problems
  • Spread tax payments and obligations more evenly
  • Improve cash flow and budgeting
  • Avoid rushed decisions in June
  • Reduce the likelihood of ATO scrutiny

Once 30 June passes, your tax position is largely locked in. Reviewing it halfway through the year gives you control, not just compliance.


Step 1: Understand Your Current Tax Position

Effective tax planning starts with clarity.

At mid-year, you should review:

  • year-to-date income
  • deductible expenses already incurred
  • profit or taxable income trends
  • cash flow and working capital
  • any loans, drawings, or shareholder transactions
  • expected income for the remainder of the year

Without accurate and up-to-date information, tax planning becomes guesswork. This is why bookkeeping, reporting, and regular reviews matter, not just at year-end.


Step 2: Review and Plan Deductible Expenses

One of the most common EOFY tax strategies involves managing deductible expenses correctly.

Mid-year is the right time to assess:

  • what expenses you typically incur each year
  • whether any necessary expenses can be brought forward
  • whether expenses are being claimed correctly

Examples may include:

  • professional fees
  • software and subscriptions
  • business-related equipment
  • interest and finance costs

The goal is not to spend unnecessarily, but to ensure legitimate business expenses are recognised in the right financial year.


Step 3: Motor Vehicle Expenses, Get This Right Early

Motor vehicle expenses are one of the most common areas where taxpayers either:

  • miss out on deductions, or
  • make incorrect claims that attract ATO attention

Mid-year is the ideal time to review:

  • whether you are using the most appropriate claim method
  • whether a logbook is required and up to date
  • business versus private use percentages
  • record-keeping processes

Waiting until June often leaves insufficient time to fix documentation issues. We explain the correct approaches and common mistakes in How to Claim Motor Vehicle Expenses.


Step 4: Superannuation Contributions as a Tax Strategy

Superannuation can be an effective tax planning tool, but only if used correctly and on time.

Mid-year planning allows you to:

  • review concessional contribution limits
  • assess whether additional contributions are appropriate
  • plan contribution timing to manage cash flow
  • avoid excess contribution penalties

Leaving super planning until June often results in rushed payments or missed opportunities, particularly where cash flow is tight.


Step 5: Income Timing and Cash Flow Considerations

For many taxpayers, especially business owners and contractors – income timing plays a critical role in tax outcomes.

Have you done your tax planning for this year?

At Pinnacle Accounting & Advisory we help Melbourne business owners plan ahead so you legally minimise this year’s tax. Book a consultation with Mina to find out where you stand.

Book a Consultation

Mid-year planning helps assess:

  • whether income is expected to increase significantly later in the year
  • how that income will impact your tax bracket
  • whether cash flow will support upcoming tax obligations

Even where income timing cannot be changed, understanding future exposure allows for better planning and fewer surprises.


Step 6: Division 7A – Address Issues Before They Escalate

Division 7A is one of the most misunderstood and costly areas of tax for company owners.

If you have:

  • taken loans from a company
  • drawn funds without formal documentation
  • used company money for personal purposes

you may already be exposed to Division 7A, even if you’re unaware of it.

Mid-year is the right time to:

  • review loan balances
  • put compliant loan agreements in place
  • plan repayments before year-end
  • avoid unfranked deemed dividends

We outline the most common and costly errors in Top 5 Division 7A Loan Traps to Avoid – essential reading for directors and shareholders.


Step 7: Review Your Business Structure and Tax Efficiency

Your business or investment structure has a significant impact on:

  • how income is taxed
  • how profits are retained or distributed
  • exposure to risk and compliance issues

Mid-year is a good checkpoint to ask:

  • Is the current structure still suitable?
  • Are profits being extracted or retained efficiently?
  • Are risks building up unnoticed?

Structural changes require time and planning. Waiting until June often means opportunities are missed for another year.


Step 8: Avoid the June Panic

One of the biggest benefits of mid-year tax planning is avoiding the June rush.

Last-minute tax planning often leads to:

  • poor decisions
  • missed deductions
  • unnecessary tax
  • higher stress

Spreading tax planning across the year results in better outcomes and better decision-making.


Final Thoughts

Mid-year tax planning in Australia is about being proactive, not reactive.

By reviewing your tax position now, you give yourself the opportunity to:

  • maximise your EOFY tax outcome
  • manage cash flow with confidence
  • reduce compliance risk
  • make informed, strategic decisions

The earlier you plan, the more options you have — and the better your long-term financial position becomes.

Watch below videos to enhance your knowledge.


Disclaimer

This article is general information only and does not constitute tax or financial advice. Always seek advice from a qualified accountant or tax agent before implementing tax strategies.

What is mid-year tax planning and why is it important in Australia?

Mid-year tax planning involves reviewing your income, expenses, and tax position halfway through the financial year. In Australia, it is important because it gives individuals and businesses time to legally reduce tax, manage cash flow, and address compliance issues before 30 June, when most planning opportunities close.

When should I start planning for my EOFY tax outcome?

The best time to start planning for your EOFY tax outcome is around January, when the financial year is halfway complete. Starting early allows you to adjust income timing, manage deductible expenses, plan superannuation contributions, and avoid rushed decisions at the end of the year.

What are the most effective EOFY tax strategies for business owners?

Effective EOFY tax strategies include reviewing deductible expenses, planning superannuation contributions, assessing motor vehicle expense claims, managing Division 7A loans, and reviewing business structure efficiency. These strategies are most effective when implemented well before 30 June.

Can mid-year tax planning help reduce the risk of ATO issues?

Yes. Mid-year tax planning helps reduce ATO risk by ensuring records are up to date, claims are correct, and compliance issues such as Division 7A loans or incorrect deductions are addressed early rather than discovered after year-end.

This article contains general advice only and does not take into account your specific circumstances. Please speak with a qualified accountant or tax adviser before making financial decisions.

Loading posts…

About Mina Baselyous

Mina Baselyous is a Chartered Tax Advisor (CTA), Certified Practising Accountant (CPA) and Registered Tax Agent based in Melbourne. He founded Pinnacle Accounting & Advisory to give small and medium business owners the proactive, strategic advice most accountants never offer. Read Mina’s full profile and credentials.

LinkedIn  |  Instagram

Read more
Start the New Year Blog Banner Pinnacle Accounting & Advisory

Start the New Year 2026 Strong: Australian Small Business Financial Checklist for January

January is the perfect time for Australian small business owners to reset, review, and realign their finances after the holiday period. A strong start to the year sets the foundation for better cash flow, fewer surprises, and smarter decisions throughout the year.

This January small business financial checklist outlines the key accounting and financial tasks business owners should focus on early in the year to stay compliant, improve profitability, and reduce stress.


1️⃣ Reconcile Bank Accounts and Clean Up Your Records

149 jpg Pinnacle Accounting & Advisory

One of the most important January accounting tasks is ensuring your bank accounts are fully reconciled.

This includes:

  • Matching bank transactions to accounting records
  • Identifying missing or duplicated entries
  • Separating personal and business transactions
  • Clearing suspense or uncategorised items

Clean records give you accurate data to work with — without this, every decision you make is based on guesswork.

If your accounts feel messy or unclear, it may be a sign that your banking structure needs improvement. We explain this in detail in below video , which outlines how proper account separation supports cash flow and compliance.


2️⃣ Review Cash Flow After the Holiday Period

626280de56a86a81b6330ba6 Ch2 why cashflow is crucial Pinnacle Accounting & Advisory

January often exposes cash flow pressure caused by:

  • reduced trading over December
  • delayed customer payments
  • increased holiday expenses

Now is the time to:

  • review current cash balances
  • assess short-term obligations
  • identify upcoming pressure points

Cash flow issues are rarely about revenue alone, they are usually linked to timing, systems, and decisions made earlier. This is closely tied to understanding your numbers properly, which we explore in The Truth About Sales & Accounting: Why Knowing Your Numbers Is the Ultimate Business Strategy.

Or Watch the video below:


3️⃣ Update Bookkeeping and Lodgements

account assets audit bank bookkeeping finance concept 53876 132604 1 Pinnacle Accounting & Advisory

January is a good time to ensure:

  • bookkeeping is up to date
  • GST coding is correct
  • payroll records are accurate
  • superannuation obligations are on track

Leaving these tasks too long increases the risk of errors, missed deductions, and ATO attention later in the year.

Strong bookkeeping early in the year makes tax planning easier and avoids last-minute pressure.


4️⃣ Check Compliance Obligations Early

Many businesses only think about compliance when deadlines arrive — January is the opportunity to plan ahead.

Key areas to review include:

  • upcoming BAS lodgements
  • superannuation payment deadlines
  • PAYG withholding obligations
  • record-keeping requirements

Being proactive here reduces risk and helps avoid penalties. If you’re unsure where your business stands, understanding how audits arise can be useful. Our audit-related content explains why poor systems and documentation often trigger issues — making early organisation critical.


5️⃣ Review Pricing, Margins, and Commercial Decisions

January is also a strategic reset point.

Ask yourself:

  • Are your prices still aligned with costs?
  • Have margins changed over the past year?
  • Are payment terms working against your cash flow?

Many financial problems don’t start in accounting software — they start in negotiation and commercial decisions.

Starting the year without a financial plan?

At Pinnacle Accounting & Advisory we help Melbourne business owners start the year with clean books, a budget and a clear plan. Book a consultation with Mina to find out where you stand.

Book a Consultation

This is why we often encourage business owners to revisit how they negotiate, not just what they sell. Our discussion on this is covered in Why Business Negotiation Skills Are Critical for Australian Business Owners.

Or watch the video below:


6️⃣ Set Financial Goals for the Year Ahead

January is the right time to set realistic, measurable financial goals, such as:

  • improving cash flow stability
  • increasing profitability (not just revenue)
  • reducing tax leakage
  • investing in systems or people

Goals should be based on actual numbers, not assumptions. Without clear data, goals quickly become wish lists.


7️⃣ Review Structures and Long-Term Planning

DrHuq ds article 19sept18 min Pinnacle Accounting & Advisory

While January is focused on short-term reset, it’s also a good checkpoint to ask:

  • Is your current structure still appropriate?
  • Are profits being retained or distributed effectively?
  • Are there risks building up unnoticed?

Many long-term problems come from ignoring structure and planning until it’s too late — the same compounding effect we see in other areas of finance and tax.


Learn More: Watch Practical Business & Finance Videos

If you prefer learning through video, our BusiHealth YouTube channel shares practical discussions on business, finance, tax, and decision-making throughout the year.

👉 Explore videos here: https://youtube.com/@BusiHealth

These videos complement our written content and help business owners understand the “why” behind financial strategies — not just the compliance side.


Final Thoughts

January is not about perfection, it’s about clarity and momentum.

By working through this small business financial checklist for January, you position your business to:

  • improve cash flow
  • stay compliant
  • make better decisions
  • reduce stress later in the year

The earlier you address financial structure, systems, and visibility, the easier the rest of the year becomes.


Disclaimer

This article is general information only and does not constitute accounting, tax, or financial advice. Always seek advice from a qualified accountant or tax agent before making financial decisions.

Why is January important for small business financial planning?

January is important because it allows business owners to review their finances after the holiday period, reset cash flow expectations, clean up bookkeeping, and plan ahead for tax and compliance obligations before issues compound later in the year.

What accounting tasks should small businesses complete in January?

Key January accounting tasks include reconciling bank accounts, updating bookkeeping records, reviewing cash flow, checking GST and superannuation obligations, and setting clear financial goals for the year ahead.

How can a January financial checklist improve cash flow?

A January financial checklist improves cash flow by identifying gaps in systems, clarifying available cash, separating tax obligations from operating funds, and addressing pricing or payment terms that may be restricting cash inflows.

Should small businesses review pricing and negotiations at the start of the year?

Yes. January is an ideal time to review pricing, margins, and negotiation practices. Decisions around pricing and payment terms directly affect profitability and cash flow throughout the year, making early review critical.

This article contains general advice only and does not take into account your specific circumstances. Please speak with a qualified accountant or tax adviser before making financial decisions.

Loading posts…

About Mina Baselyous

Mina Baselyous is a Chartered Tax Advisor (CTA), Certified Practising Accountant (CPA) and Registered Tax Agent based in Melbourne. He founded Pinnacle Accounting & Advisory to give small and medium business owners the proactive, strategic advice most accountants never offer. Read Mina’s full profile and credentials.

LinkedIn  |  Instagram

Read more
Chat with us on Messenger